User
  • Home
  • About
  • Services
    • Delaware Statutory Trust
    • Qualified Opportunity Zones
  • Marketplace
  • Guides
    • 1031 Exchange Guide
    • Qualified Opportunity Zones Guide
    • Delaware Statutory Trust Guide
  • Resources
    • All Resources
    • Accredited Investor
    • Blog
    • Guide To A 1031 Exchange
    • Guide to Qualified Opportunity Zones (QOZ, OZ)
    • Frequently Asked Questions
    • Glossary
    • Videos
    • Financial Planning
    • Due Diligence
  • Masterclasses
    • 1031 Exchange Masterclass
    • 4 Oil & Gas Tax-Smart Strategy Masterclasses 
    • QOZ Masterclass
  • Blog
  • Contact
  • Member

How Can We Help You Today?

Categories
Popular Searches
Total Results: 0 | Properties: 0 | Masterclass: 0 | Resources: 0 | Blog: 0 | Guides: 0 | Search Time: 0ms
1031 EXCHANGE
DSTs
QOZs
MASTERCLASSES
STRATEGY CALL

BOOK A STRATEGY CALL

"*" indicates required fields

Step 1 of 3 – Step 1 of 3 – What Brings You Here Today?

33%

Step 1 of 3 – What Brings You Here Today?

Select your service*

Step 2 of 3 – Schedule Your Call

Step 3 of 3 – Your Information

Untitled*
**An accredited investor, in the context of a natural person, includes anyone who: a) earned income that exceeded $200,000 (or $300,000 together with a spouse) in each of the prior two years, and reasonably expects the same for the current year, OR b) has a net worth over $1 million, either alone or together with a spouse (excluding the value of the person’s primary residence). Click here for information, or details on Accredited Entities.
Untitled*

Table of Contents:

CHAPTER 01

What Is A 1031 Exchange?

Potential Pitfalls of a 1031 Exchange

Know and Understand The Rules of a 1031 Exchange

Reasons Why An Investor May Consider A 1031 Exchange

CHAPTER 02

History of The 1031 Exchange

CHAPTER 03

Who is Eligible for A 1031 Exchange?

CHAPTER 04

Understanding Delayed
1031 Exchanges

CHAPTER 05

A Timeline for A Delayed Exchange

CHAPTER 06

Who Are The Parties

to a Delayed 1031 Exchange?

Infographic: Who Are The Parties

to a Delayed 1031 Exchange?

CHAPTER 07

Infographic: The Role of the Qualified Intermediary

BOOK A STRATEGY CALL

BOOK A STRATEGY CALL

"*" indicates required fields

Step 1 of 3 – Step 1 of 3 – What Brings You Here Today?

33%

Step 1 of 3 – What Brings You Here Today?

Select your service*

Step 2 of 3 – Schedule Your Call

Step 3 of 3 – Your Information

Untitled*
**An accredited investor, in the context of a natural person, includes anyone who: a) earned income that exceeded $200,000 (or $300,000 together with a spouse) in each of the prior two years, and reasonably expects the same for the current year, OR b) has a net worth over $1 million, either alone or together with a spouse (excluding the value of the person’s primary residence). Click here for information, or details on Accredited Entities.
Untitled*

Who is Eligible
for A 1031 Exchange?

The appeal of 1031 exchanges is obvious to savvy investors: the ability to defer, or even (through savvy estate planning) eliminate, capital gains taxes is a powerful financial incentive to consider an exchange. So let’s delve into the eligibility requirements for a 1031 exchange.

Requirement #1: The first requirement seems simple enough: to be eligible for a 1031 exchange, you must be a real estate investor, in possession of an appreciated piece of real property.

Let’s start with the simplest word: you.

For the purposes of a 1031 exchange, “you” can certainly be an individual investor. But you can also be a partnership (general or limited), a corporation (“C” or “S”), a trust, a limited liability company (LLC), or virtually any other tax-paying entity. In short, if you can own investment real estate and pay taxes on it, you can structure a 1031 exchange when selling the property in question.

Requirement #2: Both properties in the exchange—the one being sold, and the one being acquired—need to be investment real estate.

That’s another important IRS requirement: we’re talking about investment real estate here. So while individual investors are eligible, they can’t structure a 1031 exchange based on a desire to sell their primary residence or even a vacation home, and shield themselves from capital gains by investing the proceeds into a piece of investment property. Both properties in the exchange—the one being sold, and the one being acquired—need to be investment real estate. Section 1031 of the code makes it clear that properties held for use in a trade or business also qualify as investment properties for the purposes of an exchange.

A caveat: some folks have found a workaround for second homes (or vacation homes) by turning them into investment properties by renting them out for a period of time before selling. A 2007 Tax Court case determined that properties held for personal use, even with the hope or expectation of capital gains, did not qualify as investments if the investor used them exclusively for their own use, or for the use of family or friends.

A subsequent 2008 revenue procedure clarified that real properties qualified for 1031 exchanges if they were held by the investor for at least 24 months prior to (or subsequent to) the exchange, and for each of the two 12-month periods, they were rented at fair market value for at least 14 days, while restricting personal use to 14 days OR 10% of the number of days it was rented at fair market value, whichever was greater.

Requirement #3: The property being sold, or relinquished, must be an appreciated piece of real estate.

Finally, since the goal of a 1031 exchange is to defer capital gains tax for the investor, it stands to reason that the property being sold or relinquished must be appreciated real estate. As such, under ordinary circumstances, its sale would generally trigger a capital gains tax.

If you’re somehow holding a piece of investment real estate whose sale would post a loss instead of a gain, there’s no need to consider a 1031 exchange, or any other investment technique designed to minimize taxes. That’s the sole upside of a bad real estate investment: the tax man has no interest in your transaction!

Requirement #4: You must reinvest the proceeds into a like-kind exchange.

Assuming your real estate investment follows the pattern of the lion’s share of such transactions, and is subject to capital gains tax upon sale, the final requirement is your willingness as an investor to reinvest the proceeds into a like-kind exchange. In other words, you must sell your piece of investment real estate and subsequently buy another, usually more valuable, piece of real property that will also be an investment property.

Requirement #5: You must avoid a common pitfall to keep the tax man away.

If not properly structured, only a portion of a 1031 exchange might qualify for the deferral or elimination of capital gains taxes. Sometimes the replacement property is valued at a lower price than the relinquished property; the resulting difference between the two prices, known as boot, would present the investor with a tax bill based on the amount of the difference. (Learn more about Boot in Lesson 1 of Master the 1031 Exchange.)

Another common example of boot occurs when there is an unpaid mortgage on the relinquished property, but not on the replacement property. IRS regulations treat any debt the investor is relieved of as a result of the transaction as money received. So if the investor sells the relinquished property and uses the sale proceeds to pay off mortgage debt, the IRS would likely treat it as a taxable gain to the investor and tax it accordingly. The easiest way to avoid a mortgage boot is to encumber the replacement property with the same amount of debt as the relinquished property had on it.

There are other ways in which 1031 exchanges may result in boot, and several options to mitigate the situation, all of which merit a full discussion in a future chapter. For now, it’s enough to take note that actually paying the tax bill in question is a last resort, and one that can usually be avoided.

Requirement #6: You must follow strict timelines.

Ultimately, if you are ready, willing, and able to follow the timelines and other requirements prescribed by Section 1031 of the Internal Revenue Code, both your sale and your subsequent purchase will qualify for the preferential tax treatment of your resulting capital gains. We’ll examine these timelines and requirements in great detail in subsequent chapters of this guide, as we do in our 1031 Exchange Masterclass.

FAQs


What types of tax entities are eligible to execute a 1031 exchange?

Virtually any tax-paying entity capable of owning investment real estate and paying taxes on it can structure a 1031 exchange. Eligible entities include:

– Individual investors
– General or limited partnerships
– C Corporations and S Corporations
– Trusts
– Limited Liability Companies (LLCs)

Can I use a 1031 exchange for my primary residence or a vacation home?

Generally, no. Both the property being sold (relinquished) and the property being acquired (replacement) must be investment real estate or property held for use in a trade or business.
However, there is a recognized workaround for second or vacation homes based on a 2008 IRS revenue procedure. You can convert a personal vacation home into an eligible investment property if you meet the following conditions over a 24-month period (either before or after the exchange):

Rental Requirement: The property must be rented out at fair market value for at least 14 days within each of the two 12-month periods.

Personal Use Limits: Your personal use of the property cannot exceed 14 days or 10% of the total days it was rented at fair market value, whichever is greater, during each 12-month period.

What happens if my investment property sells at a net loss instead of a profit?

If a property transaction results in a loss, there is no financial reason to use a 1031 exchange. The core purpose of Section 1031 is to defer capital gains tax. If no gain is realized, no tax liability is triggered, meaning the tax man has no interest in your transaction anyway.

What is “boot,” and how does it affect my tax-deferred status?

Boot is any portion of a 1031 exchange that does not qualify for tax deferral. If an exchange is not perfectly equal or greater in value, the resulting difference is considered boot and becomes immediately taxable.

Cash Boot: Occurs when the replacement property is cheaper than the relinquished property, leaving you with leftover net cash proceeds.

Mortgage Boot (Debt Relief): Occurs when the unpaid mortgage on the replacement property is less than the mortgage on the property you sold. The IRS treats the debt you are relieved of as money received, triggering a tax bill.

Investor Tip: The most straightforward way to avoid a mortgage boot is to make sure you encumber your new replacement property with the exact same amount of debt (or more) that you held on your relinquished property.

What decides whether my transaction successfully qualifies for tax deferral?

Ultimate approval depends on strict compliance. Both your sale and subsequent purchase will only qualify for preferential tax treatment if you rigidly follow the timelines and statutory requirements prescribed by Section 1031 of the Internal Revenue Code. Failing to meet these strict deadlines will result in your entire capital gain becoming immediately taxable.

1031 EXCHANGE
DSTs
QOZs
MASTERCLASSES
STRATEGY CALL

BOOK A STRATEGY CALL

"*" indicates required fields

Step 1 of 3 – Step 1 of 3 – What Brings You Here Today?

33%

Step 1 of 3 – What Brings You Here Today?

Select your service*

Step 2 of 3 – Schedule Your Call

Step 3 of 3 – Your Information

Untitled*
**An accredited investor, in the context of a natural person, includes anyone who: a) earned income that exceeded $200,000 (or $300,000 together with a spouse) in each of the prior two years, and reasonably expects the same for the current year, OR b) has a net worth over $1 million, either alone or together with a spouse (excluding the value of the person’s primary residence). Click here for information, or details on Accredited Entities.
Untitled*

Table of Contents:

CHAPTER 01

What Is A 1031 Exchange?

Potential Pitfalls of a 1031 Exchange

Know and Understand The Rules of a 1031 Exchange

Reasons Why An Investor May Consider A 1031 Exchange

CHAPTER 02

History of The 1031 Exchange

CHAPTER 03

Who is Eligible for A 1031 Exchange?

CHAPTER 04

Understanding Delayed
1031 Exchanges

CHAPTER 05

A Timeline for A Delayed Exchange

CHAPTER 06

Who Are The Parties

to a Delayed 1031 Exchange?

Infographic: Who Are The Parties

to a Delayed 1031 Exchange?

CHAPTER 07

Infographic: The Role of the Qualified Intermediary

BOOK A STRATEGY CALL

BOOK A STRATEGY CALL

"*" indicates required fields

Step 1 of 3 – Step 1 of 3 – What Brings You Here Today?

33%

Step 1 of 3 – What Brings You Here Today?

Select your service*

Step 2 of 3 – Schedule Your Call

Step 3 of 3 – Your Information

Untitled*
**An accredited investor, in the context of a natural person, includes anyone who: a) earned income that exceeded $200,000 (or $300,000 together with a spouse) in each of the prior two years, and reasonably expects the same for the current year, OR b) has a net worth over $1 million, either alone or together with a spouse (excluding the value of the person’s primary residence). Click here for information, or details on Accredited Entities.
Untitled*

The Role of A Qualified Intermediary

CLICK HERE TO DOWNLOAD THE INFOGRAPHIC, OR VIEW IT BELOW.

The Role of the Qualified Intermediary - by Daniel Goodwin of Provident 1031 - Infographic

CLICK HERE TO DOWNLOAD THE INFOGRAPHIC OR VIEW IT BELOW.

BOOK A STRATEGY CALL WITH DANIEL GOODWIN

CONTACT FORM

"*" indicates required fields

Step 1 of 3 – Step 1 of 3 – What Brings You Here Today?

33%

Step 1 of 3 – What Brings You Here Today?

Select your service*

Step 2 of 3 – Schedule Your Call

Step 3 of 3 – Your Information

Untitled*
**An accredited investor, in the context of a natural person, includes anyone who: a) earned income that exceeded $200,000 (or $300,000 together with a spouse) in each of the prior two years, and reasonably expects the same for the current year, OR b) has a net worth over $1 million, either alone or together with a spouse (excluding the value of the person’s primary residence). Click here for information, or details on Accredited Entities.
Untitled*
The 1031 Exchange Guide by Daniel Goodwin, Chief Investment Strategist at Provident 1031
1031 EXCHANGE
DSTs
QOZs
MASTERCLASSES
STRATEGY CALL

BOOK A STRATEGY CALL

"*" indicates required fields

Step 1 of 3 – Step 1 of 3 – What Brings You Here Today?

33%

Step 1 of 3 – What Brings You Here Today?

Select your service*

Step 2 of 3 – Schedule Your Call

Step 3 of 3 – Your Information

Untitled*
**An accredited investor, in the context of a natural person, includes anyone who: a) earned income that exceeded $200,000 (or $300,000 together with a spouse) in each of the prior two years, and reasonably expects the same for the current year, OR b) has a net worth over $1 million, either alone or together with a spouse (excluding the value of the person’s primary residence). Click here for information, or details on Accredited Entities.
Untitled*

Table of Contents:

CHAPTER 01

What Is A 1031 Exchange?

Potential Pitfalls of a 1031 Exchange

Know and Understand The Rules of a 1031 Exchange

Reasons Why An Investor May Consider A 1031 Exchange

CHAPTER 02

History of The 1031 Exchange

CHAPTER 03

Who is Eligible for A 1031 Exchange?

CHAPTER 04

Understanding Delayed
1031 Exchanges

CHAPTER 05

A Timeline for A Delayed Exchange

CHAPTER 06

Who Are The Parties

to a Delayed 1031 Exchange?

Infographic: Who Are The Parties

to a Delayed 1031 Exchange?

CHAPTER 07

Infographic: The Role of the Qualified Intermediary

BOOK A STRATEGY CALL

BOOK A STRATEGY CALL

"*" indicates required fields

Step 1 of 3 – Step 1 of 3 – What Brings You Here Today?

33%

Step 1 of 3 – What Brings You Here Today?

Select your service*

Step 2 of 3 – Schedule Your Call

Step 3 of 3 – Your Information

Untitled*
**An accredited investor, in the context of a natural person, includes anyone who: a) earned income that exceeded $200,000 (or $300,000 together with a spouse) in each of the prior two years, and reasonably expects the same for the current year, OR b) has a net worth over $1 million, either alone or together with a spouse (excluding the value of the person’s primary residence). Click here for information, or details on Accredited Entities.
Untitled*

What Is A
1031 Exchange?

Let’s start with the basics: what is a 1031 exchange?

A 1031 exchange is named after the Internal Revenue Code Section that defines its rules and regulations (much like a 401(k) or 403(b) account). It helps real estate investors achieve one of the holy grails of investing: deferring capital gains taxes when selling an investment property by reinvesting the proceeds into a subsequent, similar investment property.

When done correctly, the second real estate purchase assumes the original purchase’s cost basis, and capital gains taxes are deferred until the ultimate sale of the newly acquired property. Of course, when it’s time to sell the second property, another 1031 exchange can be executed, so the business of paying taxes on your sales can, in theory, be deferred indefinitely. It’s not unheard of for savvy real estate investors to defer capital gains taxes for decades by stringing together a number of 1031 exchanges, year after year. Many professional real estate investors even use 1031 exchanges as a central component in their estate planning.

Sound simple?

Not so fast.

Potential Pitfalls
of a 1031 Exchange

While the potential benefits of a 1031 exchange are compelling enough to encourage any real estate investor to consider it, there are many potential pitfalls.

These can involve:

  • The timing of the sale and purchase of the real property in question
  • The nature of the property being sold, as well as the one being bought to replace it
  • The eligibility (and ineligibility) of certain kinds of investment properties
  • How the proceeds of each transaction are handled
  • How to address discrepancies in value (since one property is rarely exchanged for another with its exact value)
  • The process of identifying suitable properties for purchase after deciding to sell the original piece of investment real estate

These are only some of the areas in which an unaware real estate investor may run afoul of Section 1031, and any one of these critical errors could be enough to render the exchange ineligible for the valuable benefits offered by the IRS, even if all of the other rules are followed to the letter.

In the field of 1031 exchanges, such pros are known as qualified intermediaries, exchange facilitators, or exchange accommodation titleholders, and their importance to a successful, IRS-compliant transaction cannot be overstated.

Know and Understand
The Rules of a 1031 Exchange

What is true of most real estate investments is doubly true of the 1031 exchange: it is critical to know and understand the rules governing these transactions, and essential for even the most experienced real estate investors to enlist professional help to follow them all. In the field of 1031 exchanges, such pros are known as qualified intermediaries, exchange facilitators, or exchange accommodation titleholders, and their importance to a successful, IRS-compliant transaction cannot be overstated.

The common factor across these diverse factors is the deferral of capital gains taxes.

Reasons Why An Investor
May Consider A 1031 Exchange

There are many different reasons why an investor may consider using a 1031 exchange, such as:

  • They may be seeking to consolidate several properties into one (or, conversely, sell one investment property and replace it with three or more alternatives).
  • They are hoping to upgrade their investment property or invest in one with potentially higher returns.
  • They might even aim to convert a second or vacation home into an investment property through a carefully structured 1031 exchange.
  • The common factor among these diverse factors is the deferral of capital gains taxes.

That’s why I’ll be addressing every critical aspect of 1031 exchanges in this Guide to A 1031 Exchange, not only to encourage investors to consider these exchanges carefully in lieu of paying a potentially exorbitant and possibly avoidable capital gains tax, but to educate investors about the process so that they are able to take full advantage of something that the IRS rarely offers (and never offers without strings attached): a valuable tax break!

I'm A Real Estate Investing Pro: This 1031 Exchange Can Triple Your Cash Flow - by Daniel Goodwin - Published by Kiplinger 2026
BOOK A STRATEGY CALL WITH DANIEL GOODWIN

Book A Strategy Call

"*" indicates required fields

Step 1 of 3 – Step 1 of 3 – What Brings You Here Today?

33%

Step 1 of 3 – What Brings You Here Today?

Select your service*

Step 2 of 3 – Schedule Your Call

Step 3 of 3 – Your Information

Untitled*
**An accredited investor, in the context of a natural person, includes anyone who: a) earned income that exceeded $200,000 (or $300,000 together with a spouse) in each of the prior two years, and reasonably expects the same for the current year, OR b) has a net worth over $1 million, either alone or together with a spouse (excluding the value of the person’s primary residence). Click here for information, or details on Accredited Entities.
Untitled*
1031 EXCHANGE
DSTs
QOZs
MASTERCLASSES
STRATEGY CALL

BOOK A STRATEGY CALL

"*" indicates required fields

How can we help you?

Select as many as needed.
*
Start Time
:
End Time
:
Accredited Investor*
**An accredited investor, in the context of a natural person, includes anyone who: a) earned income that exceeded $200,000 (or $300,000 together with a spouse) in each of the prior two years, and reasonably expects the same for the current year, OR b) has a net worth over $1 million, either alone or together with a spouse (excluding the value of the person’s primary residence). Click here for information, or details on Accredited Entities.

Table of Contents:

CHAPTER 01

What Is A 1031 Exchange?

Potential Pitfalls of a 1031 Exchange

Know and Understand The Rules of a 1031 Exchange

Reasons Why An Investor May Consider A 1031 Exchange

CHAPTER 02

History of The 1031 Exchange

CHAPTER 03

Who is Eligible for A 1031 Exchange?

CHAPTER 04

Understanding Delayed
1031 Exchanges

CHAPTER 05

A Timeline for A Delayed Exchange

CHAPTER 06

Who Are The Parties

to a Delayed 1031 Exchange?

Infographic: Who Are The Parties

to a Delayed 1031 Exchange?

CHAPTER 07

Infographic: The Role of the Qualified Intermediary

BOOK A STRATEGY CALL

BOOK A STRATEGY CALL

"*" indicates required fields

Step 1 of 3 – Step 1 of 3 – What Brings You Here Today?

33%

Step 1 of 3 – What Brings You Here Today?

Select your service*

Step 2 of 3 – Schedule Your Call

Step 3 of 3 – Your Information

Untitled*
**An accredited investor, in the context of a natural person, includes anyone who: a) earned income that exceeded $200,000 (or $300,000 together with a spouse) in each of the prior two years, and reasonably expects the same for the current year, OR b) has a net worth over $1 million, either alone or together with a spouse (excluding the value of the person’s primary residence). Click here for information, or details on Accredited Entities.
Untitled*

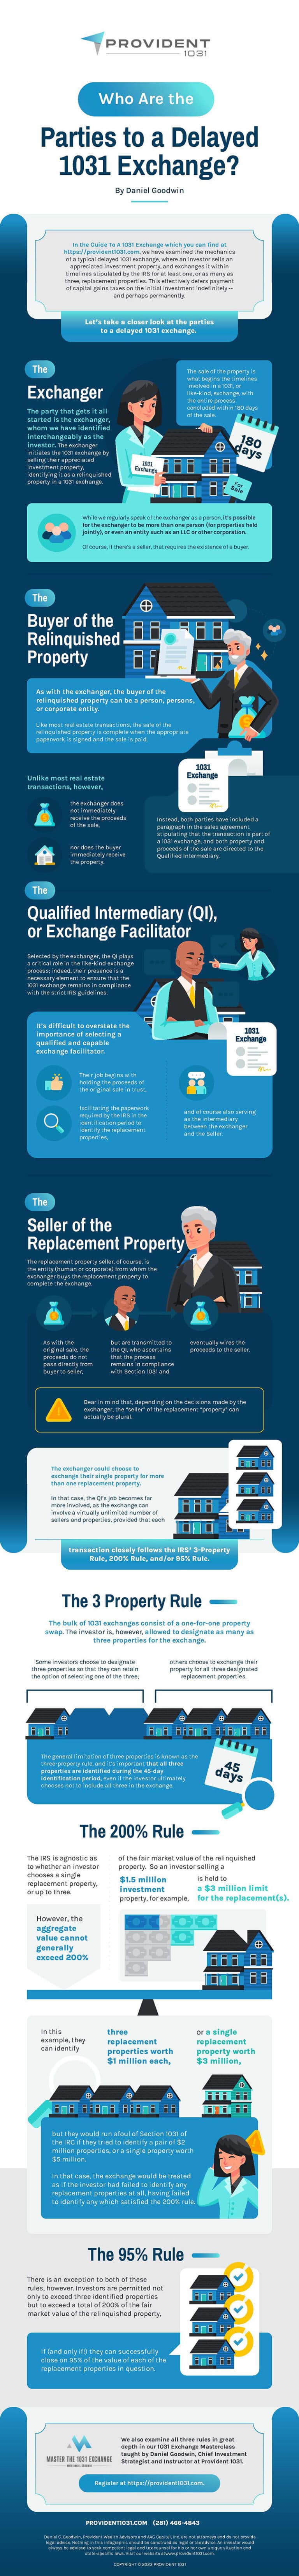
Who Are The Parties to a Delayed 1031 Exchange?

CLICK HERE TO DOWNLOAD THE INFOGRAPHIC, OR VIEW IT BELOW.

BOOK A STRATEGY CALL WITH DANIEL GOODWIN

CONTACT FORM

"*" indicates required fields

Step 1 of 3 – Step 1 of 3 – What Brings You Here Today?

33%

Step 1 of 3 – What Brings You Here Today?

Select your service*

Step 2 of 3 – Schedule Your Call

Step 3 of 3 – Your Information

Untitled*
**An accredited investor, in the context of a natural person, includes anyone who: a) earned income that exceeded $200,000 (or $300,000 together with a spouse) in each of the prior two years, and reasonably expects the same for the current year, OR b) has a net worth over $1 million, either alone or together with a spouse (excluding the value of the person’s primary residence). Click here for information, or details on Accredited Entities.
Untitled*
1031 EXCHANGE
DSTs
QOZs
MASTERCLASSES
STRATEGY CALL

BOOK A STRATEGY CALL

"*" indicates required fields

How can we help you?

Select as many as needed.
*
Start Time
:
End Time
:
Accredited Investor*
**An accredited investor, in the context of a natural person, includes anyone who: a) earned income that exceeded $200,000 (or $300,000 together with a spouse) in each of the prior two years, and reasonably expects the same for the current year, OR b) has a net worth over $1 million, either alone or together with a spouse (excluding the value of the person’s primary residence). Click here for information, or details on Accredited Entities.

Table of Contents:

CHAPTER 01

What Is A 1031 Exchange?

Potential Pitfalls of a 1031 Exchange

Know and Understand The Rules of a 1031 Exchange

Reasons Why An Investor May Consider A 1031 Exchange

CHAPTER 02

History of The 1031 Exchange

CHAPTER 03

Who is Eligible for A 1031 Exchange?

CHAPTER 04

Understanding Delayed
1031 Exchanges

CHAPTER 05

A Timeline for A Delayed Exchange

CHAPTER 06

Who Are The Parties

to a Delayed 1031 Exchange?

Infographic: Who Are The Parties

to a Delayed 1031 Exchange?

CHAPTER 07

Infographic: The Role of the Qualified Intermediary

BOOK A STRATEGY CALL

BOOK A STRATEGY CALL

"*" indicates required fields

Step 1 of 3 – Step 1 of 3 – What Brings You Here Today?

33%

Step 1 of 3 – What Brings You Here Today?

Select your service*

Step 2 of 3 – Schedule Your Call

Step 3 of 3 – Your Information

Untitled*
**An accredited investor, in the context of a natural person, includes anyone who: a) earned income that exceeded $200,000 (or $300,000 together with a spouse) in each of the prior two years, and reasonably expects the same for the current year, OR b) has a net worth over $1 million, either alone or together with a spouse (excluding the value of the person’s primary residence). Click here for information, or details on Accredited Entities.
Untitled*

A Timeline for
A Delayed Exchange

As delayed exchanges are the most common type of a 1031 exchange, it’s imperative for investors to fully understand the importance of following the timeline prescribed by the IRS in order to secure the tax benefits of successfully completing the exchange. Follow the timelines, and capital gains taxes can be deferred indefinitely, possibly even forever. But a single misstep along these carefully constructed timelines can result in the invalidation of the entire exchange, and a whopper of a capital gains tax bill to accompany it.

Before We Begin: The Selection of a Qualified Intermediary (QI)

All 1031 exchanges are facilitated by a qualified intermediary, whose first critical function is to take possession of the proceeds of the sale of the property in question. If the investor seeking to execute a 1031 exchange takes constructive receipt of these funds, little else matters; there is no possibility to execute a 1031 exchange. Accordingly, the choice of a qualified intermediary, or exchange facilitator, is central to the process, and a good QI will ensure a smooth and seamless process for the investor.

Day 1: The relinquished property is sold

The clock starts ticking on a 1031 exchange as soon as the originally-held property, also known as the relinquished property, is sold, and the proceeds of the sale are placed with a QI.

There are two critical deadlines to adhere to in a 1031 exchange: the 45-day deadline, by which at least one, and as many as three, replacement properties must be identified; and the 180-day deadline, by which the transaction(s) must be closed. The sale of the relinquished property is day one of both of these deadlines.

Day 1-45: The Identification Period

The 45 days following the sale of the relinquished property are known as the identification period. The investor must identify potential replacement properties that will constitute the second part of the 1031 exchange.

There are some rules to keep in mind as the investor identifies the property, or properties, in question. We will limit our discussion to the three most important ones.

The 3 Property Rule

The bulk of 1031 exchanges consist of a one-for-one property swap. The investor is, however, allowed to designate as many as three properties for the exchange. Some investors choose to designate three properties so that they can retain the option of selecting one of the three; others choose to exchange their property for all three designated replacement properties. The general limitation of three properties is known as the three-property rule, and it’s important that all three properties are identified during the 45-day identification period, even if the investor ultimately chooses not to include all three in the exchange.

The 200% Rule

The IRS is agnostic as to whether an investor chooses a single replacement property, or up to three. However, the aggregate value cannot generally exceed 200% of the fair market value of the relinquished property. So an investor selling a $1.5 million investment property, for example, is held to a $3 million limit for the replacement(s). In this example, they can identify three replacement properties worth $1 million each, or a single replacement property worth $3 million, but they would run afoul of Section 1031 of the IRC if they tried to identify a pair of $2 million properties, or a single property worth $5 million. In that case, the exchange would be treated as if the investor had failed to identify any replacement properties at all, having failed to identify any which satisfied the 200% rule.

The 95% Rule

There is an exception to both of these rules, however. Investors are permitted not only to exceed three identified properties but to exceed a total of 200% of the fair market value of the relinquished property, if (and only if!) they can successfully close on 95% of the value of each of the replacement properties in question. We’ll review all three of these critical rules—generally referenced as the three-property rule, the 200% rule, and the 95% rule—in much greater detail later in this guide. We also examine all three rules in great depth in our 1031 Exchange Masterclass.

One last consideration to follow during the Identification Period is the identification process itself. One way to identify a replacement property is to close on the property itself during the identification period; any property actually acquired during this 45-day period is deemed to have satisfied the identification requirement. This method makes up a minority of 1031 exchanges, though. Most investors avail themselves of the additional time by signing an Identification Notice and delivering it to the QI no later than day 45 of the identification period. (The Notice can also be delivered to the seller of the replacement property, the title company, or the escrow agent, as long as it avoids landing in the hands of a disqualified person, such as a family member of the exchanger.)

It’s critical that a properly executed Identification Notice not only be signed by the exchanger, but also provide a clear and unambiguous description of the replacement property or properties in question. Most commonly, that description is a street address or a legal description of the property, though it can also be a clearly distinguishable and commonly known name. (So while “that huge skyscraper in Houston that’s the tallest building in Texas” would be insufficient, identifying it as “600 Travis Street, Houston, TX” or “the JP Morgan Chase Tower” is clear enough.)

Where needed, the Notice should also include the percentage of the property being acquired, as well as a description of any improvements being made on the property.

Days 46 – 180 (or 1-180): The Exchange Period

Once the replacement property has been identified, the transaction is on the clock, with an intractable buzzer sounding at the conclusion of day 180. By the end of the 180th day following the sale of the relinquished property, the transaction must be closed. Failure to close it means the loss of all the tax benefits associated with a 1031 exchange. (Section 1031 of the Code actually states that the deadline is the earlier of 180 days or the Federal tax return due date for the year in which the exchange commenced; however, since the IRS routinely grants extensions to October 15th of any given year upon request, the 180 days remains the de facto deadline.)

“By the end of the 180th day following the sale of the relinquished property, the transaction must be closed. Failure to close it means the loss of all the tax benefits associated with a 1031 exchange.”

Daniel Goodwin

These Are Deadlines, Not Guidelines

The IRS is famously inflexible in general, and nowhere is this lack of wiggle room clearer than the strict deadlines of 45 days for the identification period, and 180 days for the exchange period. It matters not at all if day 45 or day 180 (or both) fall on a Saturday, Sunday, or legal holiday, nor does it matter if compelling personal circumstances, including a death in the family or other calamity, beset you as the deadline approaches. Failure to identify property by the end of day 45, or to receive the replacement property by the end of day 180, invalidates a 1031 exchange.

The only exception to this rule is if the IRS issues a Disaster Relief Notice, usually in response to a Federally declared disaster, an act of terrorism, or military action. In such cases, the IRS may elect to extend deadlines by up to 120 days. Even in such cases, it’s important to note that a declaration of disaster by a President, FEMA, or other Federal agency is not sufficient; the IRS itself must issue a formal Notice on its website.

BOOK A STRATEGY CALL WITH DANIEL GOODWIN

CONTACT FORM

"*" indicates required fields

Step 1 of 3 – Step 1 of 3 – What Brings You Here Today?

33%

Step 1 of 3 – What Brings You Here Today?

Select your service*

Step 2 of 3 – Schedule Your Call

Step 3 of 3 – Your Information

Untitled*
**An accredited investor, in the context of a natural person, includes anyone who: a) earned income that exceeded $200,000 (or $300,000 together with a spouse) in each of the prior two years, and reasonably expects the same for the current year, OR b) has a net worth over $1 million, either alone or together with a spouse (excluding the value of the person’s primary residence). Click here for information, or details on Accredited Entities.
Untitled*
1031 EXCHANGE
DSTs
QOZs
MASTERCLASSES
STRATEGY CALL

BOOK A STRATEGY CALL

"*" indicates required fields

Step 1 of 3 – Step 1 of 3 – What Brings You Here Today?

33%

Step 1 of 3 – What Brings You Here Today?

Select your service*

Step 2 of 3 – Schedule Your Call

Step 3 of 3 – Your Information

Untitled*
**An accredited investor, in the context of a natural person, includes anyone who: a) earned income that exceeded $200,000 (or $300,000 together with a spouse) in each of the prior two years, and reasonably expects the same for the current year, OR b) has a net worth over $1 million, either alone or together with a spouse (excluding the value of the person’s primary residence). Click here for information, or details on Accredited Entities.
Untitled*

Table of Contents:

CHAPTER 01

What Is A 1031 Exchange?

Potential Pitfalls of a 1031 Exchange

Know and Understand The Rules of a 1031 Exchange

Reasons Why An Investor May Consider A 1031 Exchange

CHAPTER 02

History of The 1031 Exchange

CHAPTER 03

Who is Eligible for A 1031 Exchange?

CHAPTER 04

Understanding Delayed
1031 Exchanges

CHAPTER 05

A Timeline for A Delayed Exchange

CHAPTER 06

Who Are The Parties

to a Delayed 1031 Exchange?

Infographic: Who Are The Parties

to a Delayed 1031 Exchange?

CHAPTER 07

Infographic: The Role of the Qualified Intermediary

BOOK A STRATEGY CALL

BOOK A STRATEGY CALL

"*" indicates required fields

Step 1 of 3 – Step 1 of 3 – What Brings You Here Today?

33%

Step 1 of 3 – What Brings You Here Today?

Select your service*

Step 2 of 3 – Schedule Your Call

Step 3 of 3 – Your Information

Untitled*
**An accredited investor, in the context of a natural person, includes anyone who: a) earned income that exceeded $200,000 (or $300,000 together with a spouse) in each of the prior two years, and reasonably expects the same for the current year, OR b) has a net worth over $1 million, either alone or together with a spouse (excluding the value of the person’s primary residence). Click here for information, or details on Accredited Entities.
Untitled*

Understanding
Delayed 1031 Exchanges

With 1031 exchanges offering such compelling tax advantages, the types of exchanges available have evolved over the years. Decades ago, when the Internal Revenue Code first authorized the exchanges, there was only one kind, and it was extremely limited. Now known as the simultaneous exchange, it required that the sale of the appreciated property and the acquisition of the replacement property occur at the same time.

Eventually, the code was modified to permit exchanges that allowed for some time to elapse between the sale of one property and the acquisition of the replacement property. These delayed 1031 exchanges are now the most common type of exchange, and while they are relatively straightforward to structure and execute, they must be done in accordance with the IRS rules. Any failure to follow even a single part of the procedure will result in the loss of the benefits associated with 1031 exchanges, even if all the remaining rules are followed to the letter.

Savvy real estate investors are therefore keenly aware of the following key elements of a 1031 exchange:

Finally, the Internal Revenue Code of 1954 achieved its goal of consolidating the IRC provisions from 1939-1953, revising and renumbering the existing Code sections for overall ease of operations. In so doing, Section 112(b)(1) was reborn as Section 1031 of the Internal Revenue Code, laying the groundwork for the modern structure and functions of the exchanges that bear its name.

Subsequent evolutions of 1031 exchanges broadened their appeal and deepened their value to tax-averse investors seeking to capitalize on appreciated assets while minimizing tax liability.

1. The sale of the appreciated property, and the treatment of the proceeds

When the original property is sold, it is imperative that the investor not receive the proceeds from the sale. Instead, they are sent directly from escrow to a pre-selected independent third party, known as the qualified intermediary (QI) or the 1031 exchange facilitator. These professionals know to place the funds in an independent, FDIC-insured account, taking care not to commingle these funds with those of any other investors. The funds remain in this account until they are needed to purchase the replacement property.

2. The selection of the replacement property

As soon as the proceeds from the original sale are placed with an intermediary, two important clocks start ticking: the 45-day window during which a replacement property (or properties) must be identified and the 180-day window during which the second transaction must be closed. Within the initial 45 days, the investor must identify at least one property, or as many as the 200% rule allows, to replace the relinquished property. Ideally, the property or properties in question will be equal to or greater in value than the relinquished property. (The investor can also choose a property of lesser value and commit additional funds to capital improvements; those funds will be counted towards the final net worth of the replacement property.)

Either way, the investor must identify the replacement property to the intermediary within 45 days of the closing of the first transaction; failure to do so invalidates the 1031 exchange. As far as replacement property ID rules, there are the 3-property rule, the 95% rule, and the 200% rule, which we discuss in more detail in our 1031 Exchange Masterclass taught by Daniel Goodwin.

3. Closing the deal on the replacement property

The investor has only 180 days to close on the replacement property. Accordingly, it’s usually considered best not to be overly communicative that the replacement property being sought is part of a 1031 exchange until a price is agreed upon; the owner of the replacement property would immediately understand that the investor is under a deadline, which translates into leverage for the seller and increased pressure for the buyer. Nevertheless, it is critical that not only the price be agreed upon, but also that the entire transaction be closed within 180 days of the sale of the relinquished property. As with the sale of the relinquished property, the purchase of the replacement property must be noted in the paperwork as part of a 1031 exchange.

The importance of the 45- and 180-day deadlines in a 1031 exchange cannot be overstated. The IRS is inflexible, offering adjustments to these timelines only in the event of a Presidentially declared disaster or state of emergency. Failure to complete the necessary steps within these windows, or improper processing of the 1031 exchange, may invalidate the entire exchange. Such an invalidation would subject the investor to significant taxes, possibly including treating the transaction as ordinary income rather than capital gains; ordinary income tax rates are significantly higher than capital gains tax rates, so the resulting penalty could be severe.

However, with a carefully structured transaction and the help of a professional QI or exchange facilitator, a 1031 exchange can pay you handsome dividends and defer capital gains taxes for years to come. Choosing a qualified intermediary is a critical step for the investor, as a capable, experienced QI will facilitate the transaction and ensure a seamless process.

Master The 1031 Exchange Masterclass

BOOK A STRATEGY CALL WITH DANIEL GOODWIN

Book A Strategy Call

"*" indicates required fields

Step 1 of 3 – Step 1 of 3 – What Brings You Here Today?

33%

Step 1 of 3 – What Brings You Here Today?

Select your service*

Step 2 of 3 – Schedule Your Call

Step 3 of 3 – Your Information

Untitled*
**An accredited investor, in the context of a natural person, includes anyone who: a) earned income that exceeded $200,000 (or $300,000 together with a spouse) in each of the prior two years, and reasonably expects the same for the current year, OR b) has a net worth over $1 million, either alone or together with a spouse (excluding the value of the person’s primary residence). Click here for information, or details on Accredited Entities.
Untitled*
1031 EXCHANGE
DSTs
QOZs
MASTERCLASSES
STRATEGY CALL

BOOK A STRATEGY CALL

"*" indicates required fields

Step 1 of 3 – Step 1 of 3 – What Brings You Here Today?

33%

Step 1 of 3 – What Brings You Here Today?

Select your service*

Step 2 of 3 – Schedule Your Call

Step 3 of 3 – Your Information

Untitled*
**An accredited investor, in the context of a natural person, includes anyone who: a) earned income that exceeded $200,000 (or $300,000 together with a spouse) in each of the prior two years, and reasonably expects the same for the current year, OR b) has a net worth over $1 million, either alone or together with a spouse (excluding the value of the person’s primary residence). Click here for information, or details on Accredited Entities.
Untitled*

Table of Contents:

CHAPTER 01

What Is A 1031 Exchange?

Potential Pitfalls of a 1031 Exchange

Know and Understand The Rules of a 1031 Exchange

Reasons Why An Investor May Consider A 1031 Exchange

CHAPTER 02

History of The 1031 Exchange

CHAPTER 03

Who is Eligible for A 1031 Exchange?

CHAPTER 04

Understanding Delayed
1031 Exchanges

CHAPTER 05

A Timeline for A Delayed Exchange

CHAPTER 06

Who Are The Parties

to a Delayed 1031 Exchange?

Infographic: Who Are The Parties

to a Delayed 1031 Exchange?

CHAPTER 07

Infographic: The Role of the Qualified Intermediary

BOOK A STRATEGY CALL

BOOK A STRATEGY CALL

"*" indicates required fields

Step 1 of 3 – Step 1 of 3 – What Brings You Here Today?

33%

Step 1 of 3 – What Brings You Here Today?

Select your service*

Step 2 of 3 – Schedule Your Call

Step 3 of 3 – Your Information

Untitled*
**An accredited investor, in the context of a natural person, includes anyone who: a) earned income that exceeded $200,000 (or $300,000 together with a spouse) in each of the prior two years, and reasonably expects the same for the current year, OR b) has a net worth over $1 million, either alone or together with a spouse (excluding the value of the person’s primary residence). Click here for information, or details on Accredited Entities.
Untitled*

History Of The
1031 Exchange

Since we know that 1031 exchanges offer a way to potentially defer capital gains indefinitely, we know that the root of the exchanges lies in the Internal Revenue Code, or the IRC, specifically, section 1031 of the Code. What may surprise many investors is that the exchanges are almost as old as the Code itself.

The first version of the IRC was adopted by Congress in 1918 as part of the Revenue Act of 1918, but it did not allow any tax-deferral mechanism for like-kind exchanges. Three years later, however, the Revenue Act of 1921 enabled investors to defer taxes on exchanges of securities and non-like-kind properties, enumerating these rights in Section 202(c) of the Code. Congress reversed itself quickly, eliminating the non-like-kind property provisions in the Revenue Act of 1924, and subsequently reaffirming deferral on like-kind exchanges in the Revenue Act of 1928, while also moving the relevant language to Section 112(b)(1) of the IRC.

It wasn’t until 1935 that like-kind exchanges began to more closely resemble the format we recognize today, as the Board of Tax Appeals approved like-kind exchanges that not only deferred capital gains taxes for the exchanges of similar assets, but also introduced the Qualified Intermediary as an essential part of the transaction. Importantly, the “cash in lieu of” clause, which allowed for the proceeds of the sale of one property to be exchanged for a like-kind property (instead of requiring the exchange of the properties themselves) was also upheld.

Finally, the Internal Revenue Code of 1954 achieved its goal of consolidating the IRC provisions from 1939 to 1953, revising and renumbering existing Code sections to improve overall ease of operation. In so doing, Section 112(b)(1) was reborn as Section 1031 of the Internal Revenue Code, laying the groundwork for the modern structure and functions of the exchanges that bear its name.

Subsequent evolutions of 1031 exchanges broadened their appeal and deepened their value to tax-averse investors seeking to capitalize on appreciated assets while minimizing tax liability.

We’ve used the terms “1031 exchange” and “like-kind exchange” interchangeably; they are also frequently referred to as “Starker exchanges,” or “Starker trusts.”

We’ve used the terms “1031 exchange” and “like-kind exchange” interchangeably; they are also frequently referred to as “Starker exchanges,” or “Starker trusts.” The name stems from a 1979 court case, Starker v. United States, in which the Starker family contested the IRS decision that their sale of timberland to a corporation, in exchange for a contractual promise to acquire and transfer title to properties identified by the Starkers within five years, did not qualify for a deferral of their income tax liabilities. The eventual decisions from the Ninth Circuit Court of Appeals set the precedent for what we now know as non-simultaneous, delayed like-kind exchanges. The Starker decisions also forced Congress to establish regulations governing non-simultaneous, delayed like-kind exchanges. As a result, the Deficit Reduction Act of 1984 introduced the 45-calendar-day identification deadline and the 180-calendar-day exchange period. We’ll be discussing these important timelines in greater detail in future sections of this guide.

Not long after, the Tax Reform Act of 1986 changed the treatment of capital gains, treating all capital gains as ordinary income.

Not long after, the Tax Reform Act of 1986 changed the treatment of capital gains, treating all capital gains as ordinary income. Combined with a handful of accounting changes that accompanied the capital gains tax treatment, the 1031 exchange emerged as one of the few and best remaining income tax benefits available to investors, especially those with real property investments.

In 1990, the Department of the Treasury proposed rules that codified and finalized the 45- and 180-day timelines first established in 1984. They also provided guidance on constructive receipt issues, clarified the definitions of “simultaneous” and “improvement” exchanges under Section 1031, and further defined the eligibility of Qualified Intermediaries under Section 1031. These proposed rules were issued as final regulations in June of 1991, and remain an integral basis of 1031 exchanges today.

While other minor tweaks helped to form the current version of the 1031 exchange, the only other major development was the IRS’s decision to issue Revenue Ruling 2004-86, which paved the way for investors to take fractional ownership of interests in real property through Delaware Statutory Trusts, or DSTs. By ruling that DSTs qualified as a suitable replacement property for investors seeking to execute a 1031 exchange, it provided investors with an alternative to seeking out one or more real properties on their own, in theory, facilitating increased participation in 1031 exchanges.

As the foregoing history demonstrates, 1031 exchanges have existed for decades and are likely to continue in some form for generations to come. Their evolution also demonstrates the ongoing need for investors to remain vigilant regarding any legislative attempts to strengthen this important tax benefit – or to weaken it. Multiple attempts have been made over the years to alter or even eliminate Section 1031 benefits, and while none have succeeded thus far, future attempts are virtually certain.

Our goal here, and in our Master The 1031 Exchange Masterclass, is not only to educate you on the current state of 1031 exchanges but also to keep you informed of any future changes.

BOOK A STRATEGY CALL WITH DANIEL GOODWIN

CONTACT FORM

"*" indicates required fields

Step 1 of 3 – Step 1 of 3 – What Brings You Here Today?

33%

Step 1 of 3 – What Brings You Here Today?

Select your service*

Step 2 of 3 – Schedule Your Call

Step 3 of 3 – Your Information

Untitled*
**An accredited investor, in the context of a natural person, includes anyone who: a) earned income that exceeded $200,000 (or $300,000 together with a spouse) in each of the prior two years, and reasonably expects the same for the current year, OR b) has a net worth over $1 million, either alone or together with a spouse (excluding the value of the person’s primary residence). Click here for information, or details on Accredited Entities.
Untitled*
  • Home
  • About
  • Marketplace
  • Guides
  • Masterclasses
  • Masterclasses
  • Blog
  • Contact
  • Privacy Policy
  • Terms & Conditions
  • ADV-2A
  • user
  • share
  • mail
  • X
  • facebook
  • linkedin
  • youtube
  • reddit
  • quora

(281) 466-4843

25511 Budde Rd, Suite 1003, The Woodlands, TX 77380

© Copyright 2026 - Provident 1031. All Rights Reserved.

SECURITIES DISCLOSURE

There are material risks associated with investing in DST and QOZ ( Qualified Opportunity Zones) properties and alternative real estate securities including liquidity, tenant vacancies, general market conditions and competition, lack of operating history, interest rate risks, the risk of new supply coming to market and softening rental rates, general risks of owning/operating commercial and multifamily properties, short term leases associated with multi-family properties, financing risks, potential adverse tax consequences, general economic risks, development risks, long hold periods, and potential loss of the entire investment principal. Past performance is not a guarantee of future results. Potential cash flow, returns and appreciation are not guaranteed. IRC Section 1031 is a complex tax concept; consult your legal or tax professional regarding the specifics of your situation. This is not a solicitation or an offer to sell any securities. Investing in real estate and DSTs is speculative, illiquid, involves a high degree of risk, may result in total loss and is not suitable for all investors.

THIS IS NEITHER AN OFFER TO SELL NOR A SOLICITATION OF AN OFFER TO BUY THE SECURITIES DESCRIBED HEREIN. AN OFFERING IS MADE ONLY THROUGH DELIVERY OF THE PPM and to accredited investors only. THIS MATERIAL MUST BE PRECEDED OR ACCOMPANIED BY A CURRENT PPM WHICH SHOULD BE READ IN ITS ENTIRETY IN ORDER TO UNDERSTAND FULLY ALL OF THE IMPLICATIONS AND RISKS OF THE OFFERING OF SECURITIES TO WHICH IT RELATES.

Please consult the appropriate professional regarding your individual circumstances. Alternative investments are often sold by prospectus that discloses all risks, fees, and expenses.

For additional information, please contact (281) 466-4843 or www.Provident1031.com. Fee-based financial planning and investment advisory services are offered by Provident Wealth Advisors, a Registered Investment Advisor in the State of Texas, and the State of Louisiana.

Insurance products and services are offered through Goodwin Financial Group. Provident Wealth Advisors and Goodwin Financial Group are affiliated companies. Provident Wealth Advisors, LLC does not offer legal or tax advice. Consult the appropriate professional regarding your individual circumstance.

Securities Offered through Quincy Wells Capital, LLC. Member FINRA/SIPC. The presence of this website shall in no way be construed or interpreted as a solicitation to sell or offer to sell investment advisory services to any residents of any State other than the State of Texas or where otherwise legally permitted. Important Notice – If you are investing in Alternatives your tax advisor may require you to file a tax return in the state where the subject property is located which could result in additional costs associated with your investment. Any additional expenses associated with any required tax filing are the sole responsibility of the investor/client.

Information about securities-registered professionals may be found at FINRA BROKERCHECK. Member FINRA/IEX/SIPC.

Information about securities-registered professionals may be found at FINRA BROKERCHECK.   Member FINRA/IEX/SIPC. 

Looking For A Qualified Intermediary

"*" indicates required fields

Name*
Schedule Consultation

Name
Connect with a Qualified Intermediary

"*" indicates required fields

Name*
Schedule a Consultation

Name
Subscribe to Provident 1031

Name
Cleantalk Pixel
×

"*" indicates required fields

Step 1 of 3 - Step 1 of 3 - What Brings You Here Today?

33%

Step 1 of 3 - What Brings You Here Today?

Select your service*

Step 2 of 3 - Schedule Your Call

Step 3 of 3 - Your Information

Untitled*
**An accredited investor, in the context of a natural person, includes anyone who: a) earned income that exceeded $200,000 (or $300,000 together with a spouse) in each of the prior two years, and reasonably expects the same for the current year, OR b) has a net worth over $1 million, either alone or together with a spouse (excluding the value of the person’s primary residence). Click here for information, or details on Accredited Entities.
Untitled*